Call us today on 01297 692 200 to find out how BGA Accountants can help you!
Blog
Latest Blog & Articles
Stay informed with expert financial insights! Explore our latest blogs on wealth management, retirement planning, and smart investment strategies. Empower your financial future with practical tips and expert advice.
SDLT on mixed-use property
Stamp duty land tax (SDLT) is payable on the purchase of a property in England or Northern Ireland.
There are different rates for residential properties (with a 5% supplement applying to second and subsequent residential properties) and non-residential properties. The non-residential rates also apply to mixed-use properties. The starting point for residential properties is than for non-residential properties and the rates are higher and the rates applicable to residential properties are higher. Thus, the SDLT bill will be lower for a mixed-use property than for a residential property of the same price.
Is the property a mixed-use property?
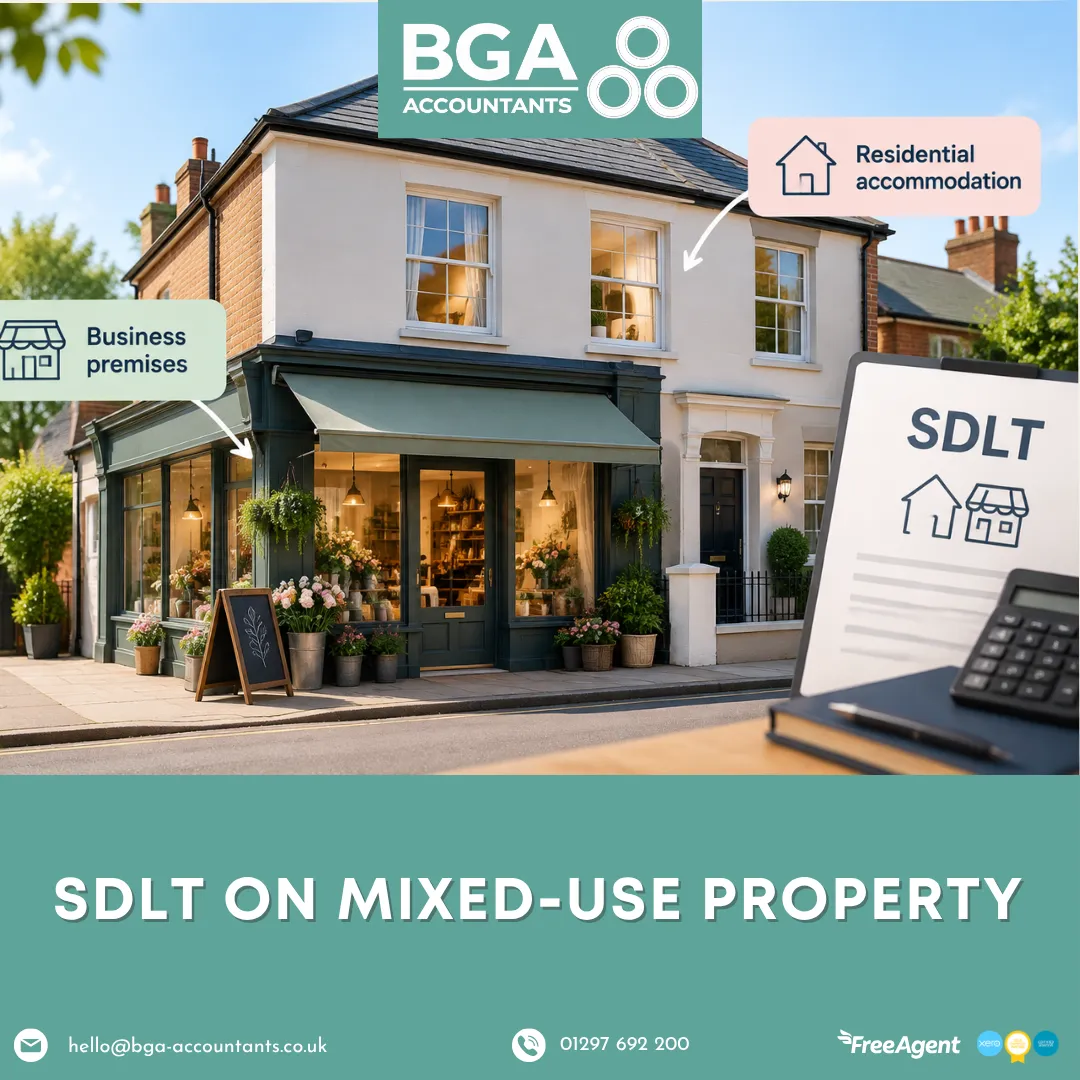
The fact that part of a property is used for business will not in itself make a property a mixed-use property. HMRC draw a distinction between the use of certain rooms for business in what otherwise would be a dwelling (for example, the use of one room as a home office) and a building containing residential accommodation which has been divided into separate areas, one or more of which is used as commercial or business premises (for example, where part of a house has been converted into a shop).
Where a room in a house is used as a home office or similar, the room usually remains suitable for use as part of the dwelling house. Consequently, the property is a dwelling house not a mixed-use property and as such the residential stamp duty rates apply. Using the dining room as an office does not make a dwelling a mixed-use property.
Where the property is converted, or used without specific conversion, as part residential accommodation and part commercial and sold as a single interest, the position is more nuanced. Where part of the building is set aside for day-to-day commercial use and that part is used separately from the parts used for accommodation, HMRC will accept that the parts used commercially are not part of the dwelling. Consequently, the property is a mixed-use property and the non-residential SDLT rates will apply. An example here would be a house in which two rooms are dedicated to use as a hairdressers; the rooms converted into the hairdressers are not part of the living accommodation.
It is important to note that the use of the rooms does not in itself determine whether the property is a mixed-use property; the degree of conversion and the degree of separation from the living accommodation are key. If the rooms used commercially can easily be incorporated into the residential parts of the building without the need for any adaptation, they will remain part of the dwelling house and the property will not be a mixed-use property for SDLT purposes. However, if the parts used commercially have been converted in such a way that the rooms are not suitable for living accommodation (for example, where part of the property has been converted into a shop, a separate entrance and the installation of shelving, fridges etc.), then the part so converted will no longer be suitable for use as living accommodation; the property will be a mixed-use property and the non-residential SDLT rates will apply.
The BGA Difference
Simple, Honest Advice — With No Surprises
We work on fixed monthly fees, with unlimited calls and meetings included — so you can ask questions anytime, without worrying about the cost.
Your first meeting and initial advice are always free.
We speak plain English, not accountancy jargon. You shouldn’t need a finance degree to understand your own numbers — and we’ll explain everything clearly so you feel confident, not confused.
We’ve seen it time and again: when clients understand their accounts and taxes, they make better decisions. That’s why we focus on accessible advice, regular check-ins, and smart tax planning throughout the year.
We're not the cheapest Accountant around and we don't want to be! We provide a reliable, quality service at a fair price.
Contact
Opening hours
Monday - Thursday : 9:00AM - 5PM
Helping you achieve financial success with expert guidance and personalised strategies.
© BGA Accountants. 2026. All Rights Reserved.
PRIVACY POLICY | SUPPORT | TERMS & CONDITION